Can You Get a Home Loan with Low Income?
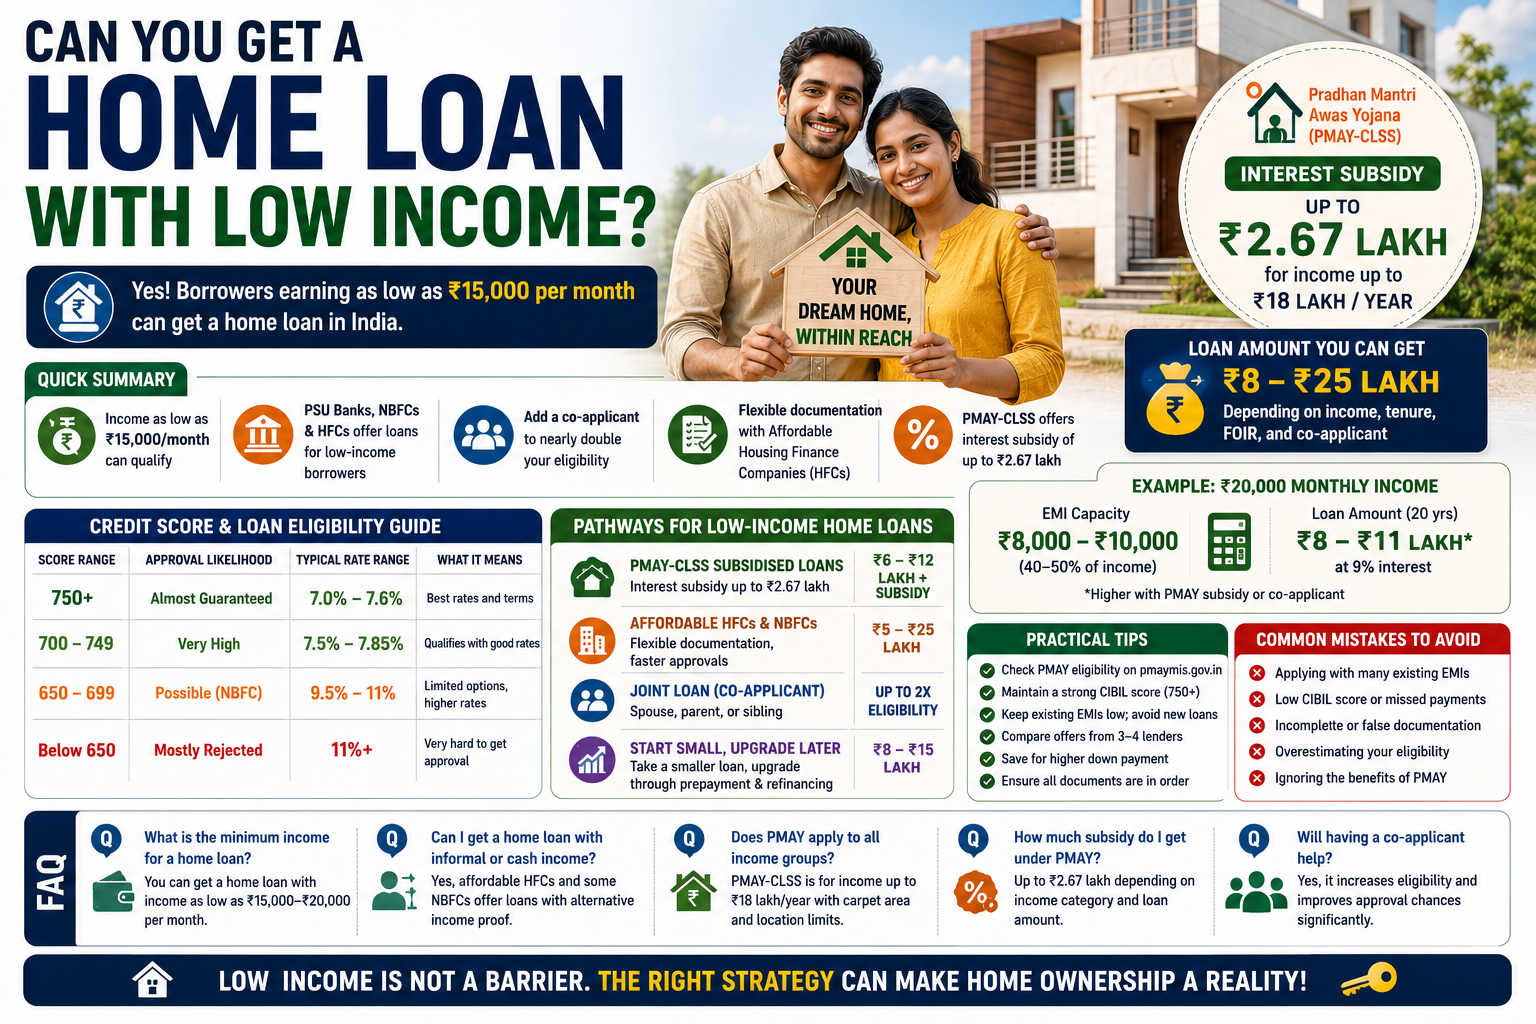
Yes, you can absolutely get a home loan with low income in India — banks and government-backed schemes regularly approve home loans for borrowers earning ₹15,000–30,000 per month. In this guide, you’ll learn the loan amount you can realistically expect, special schemes available, and strategies to maximise your eligibility.
Quick Summary
- Borrowers with monthly income as low as ₹15,000 can get home loans from PSU banks, NBFCs, and HFCs.
- The Pradhan Mantri Awas Yojana (PMAY-CLSS) offers interest subsidies of up to ₹2.67 lakh for income up to ₹18 lakh/year.
- Low-income borrowers typically qualify for ₹8–25 lakh loans depending on tenure, FOIR, and co-applicant.
- Adding a co-applicant (spouse, parent, sibling) can almost double eligibility.
- Affordable housing finance companies (HFCs) specialise in serving low-income borrowers with flexible documentation.
Low-Income Home Loan Pathways
| Pathway | Loan Range | Best For |
|---|---|---|
| PMAY-CLSS subsidised | ₹6–12 lakh + subsidy | Income up to ₹18 lakh/year, first home |
| Affordable HFCs | ₹5–25 lakh | Self-employed, informal sector |
| Joint loan (spouse/parent) | Up to 2x individual eligibility | Dual-income households |
| Small loan + future upgrade | ₹8–15 lakh | Conservative borrowers, building savings |
When to Choose PMAY vs Affordable HFC
Opt for PMAY-CLSS if: Your annual household income is up to ₹18 lakh, this is your first home, and the property’s carpet area meets the scheme’s caps.
Go to an affordable HFC if: You’re self-employed without consistent ITRs, work in informal sectors, or need flexible income documentation.
If you want to estimate how much you may be able to borrow based on your income and existing obligations, read Home Loan Eligibility Calculator: How It Works and What It Misses before deciding on a loan amount.
Practical Tips
- Check your PMAY eligibility on the official portal (pmaymis.gov.in) before applying.
- Maintain a strong CIBIL score (aim for 750+).
- Add a working spouse or parent as co-applicant to combine incomes.
- Start with a property within ₹10–20 lakh range — over-borrowing at low income is the fastest path to default.
To understand how combining eligible incomes can increase your borrowing capacity, read Joint Home Loan: How Adding a Co-Applicant Increases Your Eligibility.
Common Mistakes to Avoid
- Borrowing the maximum eligibility — leaves no buffer for emergencies.
- Skipping PMAY application thinking “it’s complicated” — most banks process the subsidy paperwork for you.
- Concealing existing informal debts.
FAQ
Can I get a home loan with a salary of ₹15,000 per month?
Yes, a ₹15,000 monthly salary can qualify for a home loan of approximately ₹6–8 lakh from PSU banks, NBFCs, and affordable HFCs.
What is PMAY-CLSS and how does it help low-income borrowers?
PMAY-CLSS provides upfront interest subsidies of ₹2.30–₹2.67 lakh for first-time buyers in three income categories, credited directly to your loan account.
Which banks offer home loans for low-income borrowers?
Major PSU banks (SBI, Bank of Baroda, PNB) and affordable HFCs like Aadhar Housing Finance, Aavas Financiers, and India Shelter Finance.
Do I need a co-applicant to get a home loan with low income?
A co-applicant is not mandatory but strongly recommended — it can nearly double your eligibility.
What documents are required for a low-income home loan?
Identity proof, address proof, last 3 months’ salary slips or 6 months’ bank statements, property documents, and PMAY declarations if applicable.