How to Improve a FOIR That’s Too High Before You Reapply
If your home loan application was rejected because your FOIR was too high, the best approach is to reduce your existing monthly obligations, increase your documented income, or lower the loan amount you plan to borrow before reapplying.
You should also check the lender’s own eligibility criteria because there is no single FOIR limit that applies to every lender or borrower.
What Does a High FOIR Mean for Your Home Loan?
A high FOIR means a large share of your income is already committed to fixed financial obligations, leaving less room for a new home loan EMI. Lenders use FOIR as one part of their assessment of repayment capacity.
A simple way to understand it is:
FOIR = Monthly fixed obligations ÷ Monthly income × 100
For example, suppose you earn ₹80,000 a month and already pay ₹35,000 towards loans and other obligations. If a proposed home loan adds another ₹25,000 EMI, your total monthly obligations become ₹60,000.
Your resulting ratio would be:
₹60,000 ÷ ₹80,000 × 100 = 75%
That may be too high for the lender assessing your application. However, the acceptable level varies by lender, income profile, existing liabilities and other underwriting factors. It is better to treat any percentage as lender-specific rather than assume that 40%, 50% or 60% is a universal rule.
Why Was Your FOIR Too High?
Your FOIR may be high because of existing EMIs, credit-card obligations, a large proposed home loan, or income that the lender does not fully recognise for eligibility purposes.
Before reapplying, identify exactly what is pushing the ratio up:
- Personal loan or car loan EMIs
- Existing home loan or other secured-loan obligations
- Credit-card dues or other recurring credit obligations considered by the lender
- A large proposed home loan EMI
- Income that is variable, insufficiently documented or not fully considered by the lender
- A short repayment tenure that produces a higher proposed EMI
The first step is therefore not simply to “wait and reapply.” It is to identify which part of the calculation needs to change.
How to Reduce FOIR Before Reapplying
You can improve a high FOIR by reducing existing obligations, increasing recognised income, adjusting the proposed loan, or strengthening the overall application.
1. Close or reduce smaller existing loans
Reducing an existing EMI can have a direct effect on your FOIR because it lowers the monthly obligation used in the assessment. Paying off a small personal loan or another loan close to maturity may therefore make more sense than immediately applying again.
For example, if your monthly obligations fall from ₹35,000 to ₹20,000 on an ₹80,000 income, the ratio falls from:
43.75% to 25%
before considering the proposed home-loan EMI.
Do not empty your emergency savings simply to improve FOIR. The objective is to reduce debt without creating a separate financial problem.
2. Avoid taking new loans before reapplying
Taking a personal loan, consumer loan or other new credit shortly before reapplying can increase your monthly obligations and work against your objective.
If the home purchase is your priority, avoid adding unnecessary debt between applications. Focus on reducing existing liabilities and keeping your repayment record clean.
3. Increase the down payment if possible
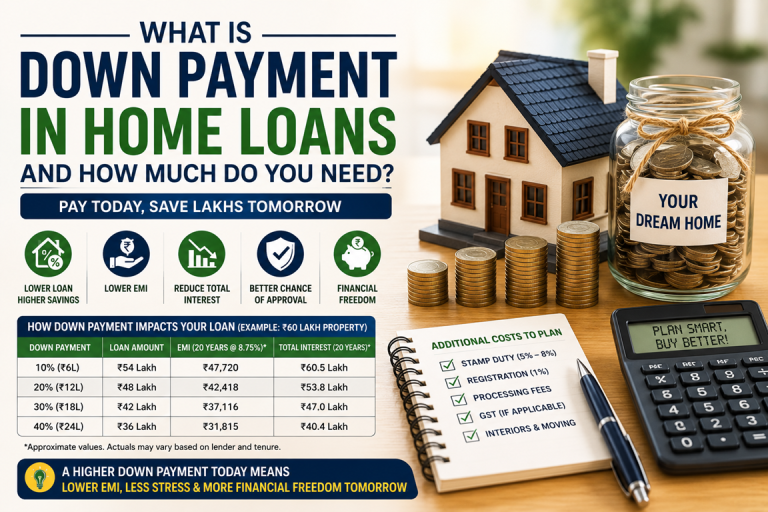
A larger down payment can reduce the amount you need to borrow, which can reduce the proposed home-loan EMI. That can improve your overall repayment profile.
For example, if you planned to borrow ₹50 lakh but can comfortably increase your own contribution and reduce the loan requirement, the resulting EMI may be lower.
However, do not use all your available cash for the down payment. Keep enough money for registration and other purchase costs, moving expenses and an emergency reserve.
4. Increase your documented income
If your actual income has increased since your previous application, make sure the lender can verify it through appropriate documents.
For salaried applicants, this may include updated salary records and bank statements. Self-employed applicants may need documents such as ITRs, financial statements and bank statements, depending on the lender’s requirements.
A higher recognised monthly income can improve repayment capacity without requiring you to take on additional debt.
5. Consider a financially suitable co-applicant
Adding an eligible co-applicant with stable income can potentially strengthen loan eligibility because the lender may assess the combined financial profile. Some lenders explicitly provide for co-applicant income in their eligibility calculations.
However, a co-applicant is not simply a way to “fix” FOIR. Their existing obligations, credit history, income and relationship to the borrower may also affect the assessment.
6. Reduce the home loan amount you are requesting
Sometimes the problem is not your existing debt but the size of the new loan you are seeking.
If your existing obligations cannot be reduced quickly, consider a lower property budget or a larger down payment. A smaller loan means a smaller proposed EMI, which can bring the overall obligation closer to the lender’s acceptable range.
How Long Should You Wait Before Reapplying?
You should reapply when your financial profile has materially improved rather than simply waiting a fixed number of weeks or months. There is no universal RBI-mandated waiting period for a borrower whose home loan application was rejected because of a high FOIR.
Before submitting another application, check whether you have actually changed the factor that caused the rejection:
| Problem | Better step before reapplying |
|---|---|
| High existing EMIs | Repay or reduce an existing loan |
| Large proposed EMI | Reduce loan amount or increase down payment |
| Income not fully recognised | Improve income documentation |
| Multiple financial obligations | Reduce unnecessary debt |
| Single-income application | Consider an eligible co-applicant |
| Unclear eligibility | Recalculate eligibility before applying |
If the lender rejected the application, ask for the reason and review the specific issue rather than making several applications without changing your profile. RBI guidance requires lenders to communicate reasons for rejection within the applicable framework.
Check Your FOIR Before You Apply Again
Checking eligibility before submitting another formal application can help you avoid repeating the same problem.
With our New Home Loan Eligibility Checker, you can enter your monthly income, existing EMIs, expected interest rate, tenure and co-applicant details to get an estimate of your borrowing capacity. Our calculator currently uses a backend assumption of up to 55% of monthly income for total EMIs; this is a Nestara estimation policy, not a universal lender or RBI FOIR limit.
You can then compare the result with the loan amount you actually need and decide whether you should reduce your obligations, increase your contribution or reconsider the property budget.
Conclusion: Fix the Ratio Before You Reapply
A high FOIR is not necessarily a permanent barrier to getting a home loan. The practical solution is to identify what is driving the ratio and change that part of your financial profile before submitting another application.
Start by reviewing your existing EMIs, avoid taking on fresh debt, improve documented income where possible, consider a suitable co-applicant and reduce the proposed loan amount if necessary. Then use Nestara’s home loan eligibility checker to estimate your position before making another application. That extra check can help you approach the next lender with a more realistic loan requirement and a stronger repayment profile.
FAQs
1. What is a good FOIR for a home loan?
There is no single FOIR percentage that applies to every home loan applicant. Lenders use their own credit and underwriting policies, and the assessment can vary based on income, existing liabilities, credit profile and other factors.
2. Can I get a home loan if my FOIR is high?
You may still qualify, but a high FOIR can reduce the loan amount you are eligible for or make approval more difficult. Reducing existing obligations, increasing recognised income or requesting a smaller loan may improve your position.
3. Does paying off a personal loan improve FOIR?
Yes, if that loan’s EMI is included in the lender’s obligation calculation. Removing the EMI reduces your monthly fixed obligations and can therefore lower your FOIR.
4. Does increasing the down payment reduce FOIR?
It can reduce the proposed home-loan EMI because you borrow less. Since the new EMI forms part of the repayment obligation assessed by the lender, this can improve your overall ratio.
5. Can adding a co-applicant reduce my FOIR?
A suitable co-applicant can strengthen the combined application if their eligible income is considered. However, the lender may also consider the co-applicant’s existing obligations and credit profile, so the effect is not automatically positive.
6. Should I apply to another bank if my FOIR is too high?
You can compare lenders, but applying repeatedly without addressing the underlying issue may not solve the problem. First understand why your application was rejected, improve the relevant financial factor, and then compare suitable options.