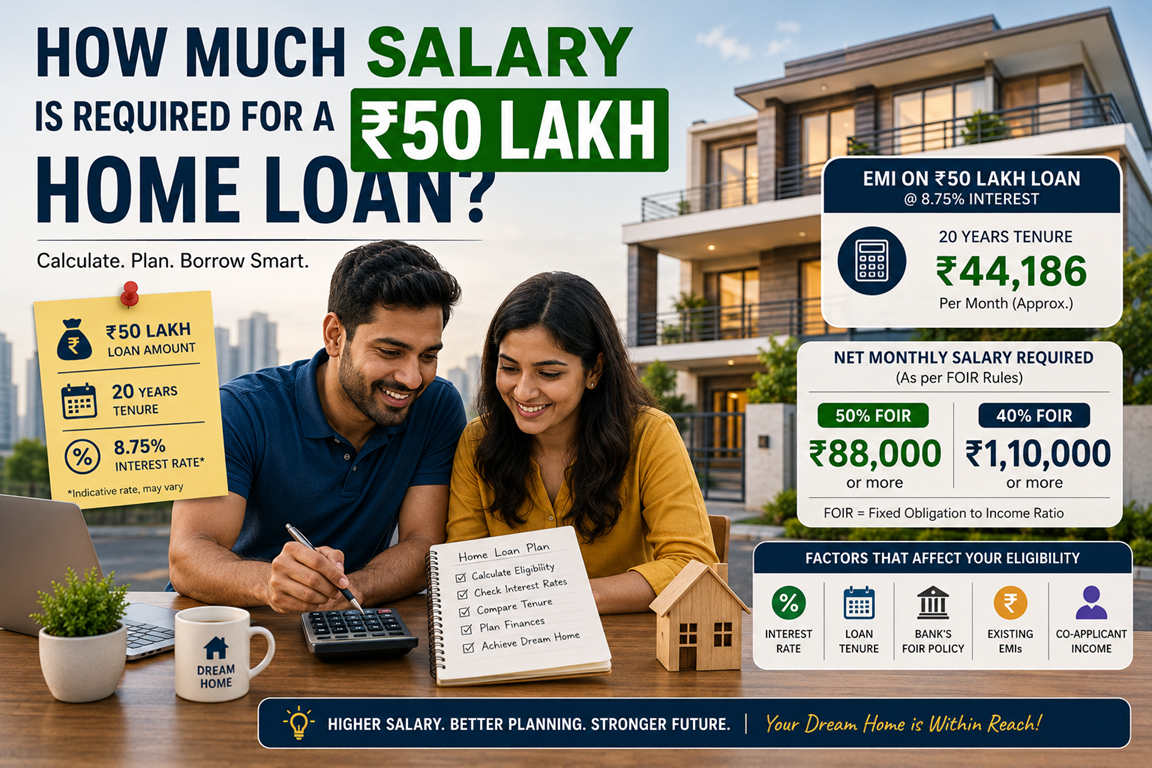
How Much Salary Is Required for a ₹50 Lakh Home Loan?
For a ₹50 lakh home loan over 20 years, you typically need a net monthly salary of around ₹85,000–₹1,10,000, depending on existing EMIs, lender policy, and interest rate. In this guide, you’ll learn the exact salary calculation and how to maximise your eligibility.
Quick Summary
- For a ₹50 lakh, 20-year home loan at 8.75%, EMI is approximately ₹44,186 — requiring a net salary of ₹88,000–₹1,10,000.
- Lenders use the FOIR rule: total EMIs (existing + new) cannot exceed 40–50% of net monthly income.
- Extending tenure to 25 or 30 years lowers EMI and the salary requirement, but increases total interest paid.
- Adding a co-applicant (spouse) can effectively combine incomes, unlocking the loan at lower individual salary.
- CIBIL score, age, and employment stability also influence approval beyond just salary.
Use our Loan to Salary Calculator to get the exact amount
Salary Requirements by Strategy
| Strategy | EMI on ₹50L | Salary Needed (50% FOIR) |
|---|---|---|
| 20-year tenure @ 8.75% | ₹44,186 | ₹88,372 |
| 25-year tenure @ 8.75% | ₹41,113 | ₹82,226 |
| 30-year tenure @ 8.75% | ₹39,335 | ₹78,670 |
| Add co-applicant (₹40K income) | ₹44,186 | Combined ₹88K achievable |
| Reduce loan to ₹40L | ₹35,349 | ₹70,698 |
If you want to compare how different loan amounts, interest rates and repayment tenures affect your borrowing capacity, read Home Loan Eligibility Calculator: How It Works and What It Misses before deciding how much to borrow.
Key Factors
- Interest Rate — Each 0.5% lower saves ~₹1,500/month in EMI
- Tenure — Each extra 5 years lowers EMI by 5–10%
- Bank’s FOIR — 40% strict vs 50% lenient
- Existing EMIs — Each ₹1,000 raises required salary ~₹2,000–2,500
- Variable Income Inclusion — Bonuses count partially in some banks
To understand how your existing loan repayments affect your borrowing capacity, read What Is FOIR (Fixed Obligation to Income Ratio) and How to Improve It, which explains how lenders assess fixed obligations against income.
When to Stretch Tenure vs Add Co-Applicant
Stretch tenure to 25–30 years if: Your salary is at the lower end and you want EMI well within comfortable limits. You can always prepay later.
Add a co-applicant instead if: You have a partner with stable income and don’t want to extend tenure or pay more total interest.
Practical Tips
- Use online EMI calculators to test different tenure, rate, and loan amount combinations.
- Pay off small personal loans, BNPL, or credit card balances 2–3 months before applying.
- Choose a lender with 50% FOIR if your salary is borderline.
- Don’t max out eligibility — borrowing what your salary “allows” leaves no buffer.
Common Mistakes to Avoid
- Considering only gross salary instead of net (take-home) — banks calculate FOIR on net.
- Including unrealistic variable income (bonuses, incentives).
- Stretching tenure to 30 years just because the bank allows it.
FAQ
What is the minimum salary for a ₹50 lakh home loan in India?
The minimum net monthly salary is approximately ₹85,000–₹90,000 at 50% FOIR, 20-year tenure, 8.75% rate.
Can I get a ₹50 lakh home loan with a ₹70,000 salary?
A ₹70,000 net salary falls short for standard 20-year tenure. Qualify by extending tenure to 30 years, adding a co-applicant, reducing loan to ₹40 lakh, or finding a lender with 55–60% FOIR.
Does a higher down payment reduce the salary required?
Yes — increasing down payment reduces the loan amount, which directly reduces EMI and salary required.
How does my CIBIL score affect ₹50 lakh loan approval?
A 750+ score typically gets the best rates (8.5–8.75%), while a 700–749 score may attract 9–9.5%, increasing EMI by ₹2,000–3,000/month.
Should I take a ₹50 lakh loan with my current salary or wait?
Take the loan now if your salary comfortably supports the EMI (under 40% FOIR) and finances are in order. Wait if salary is borderline or CIBIL is below 750.