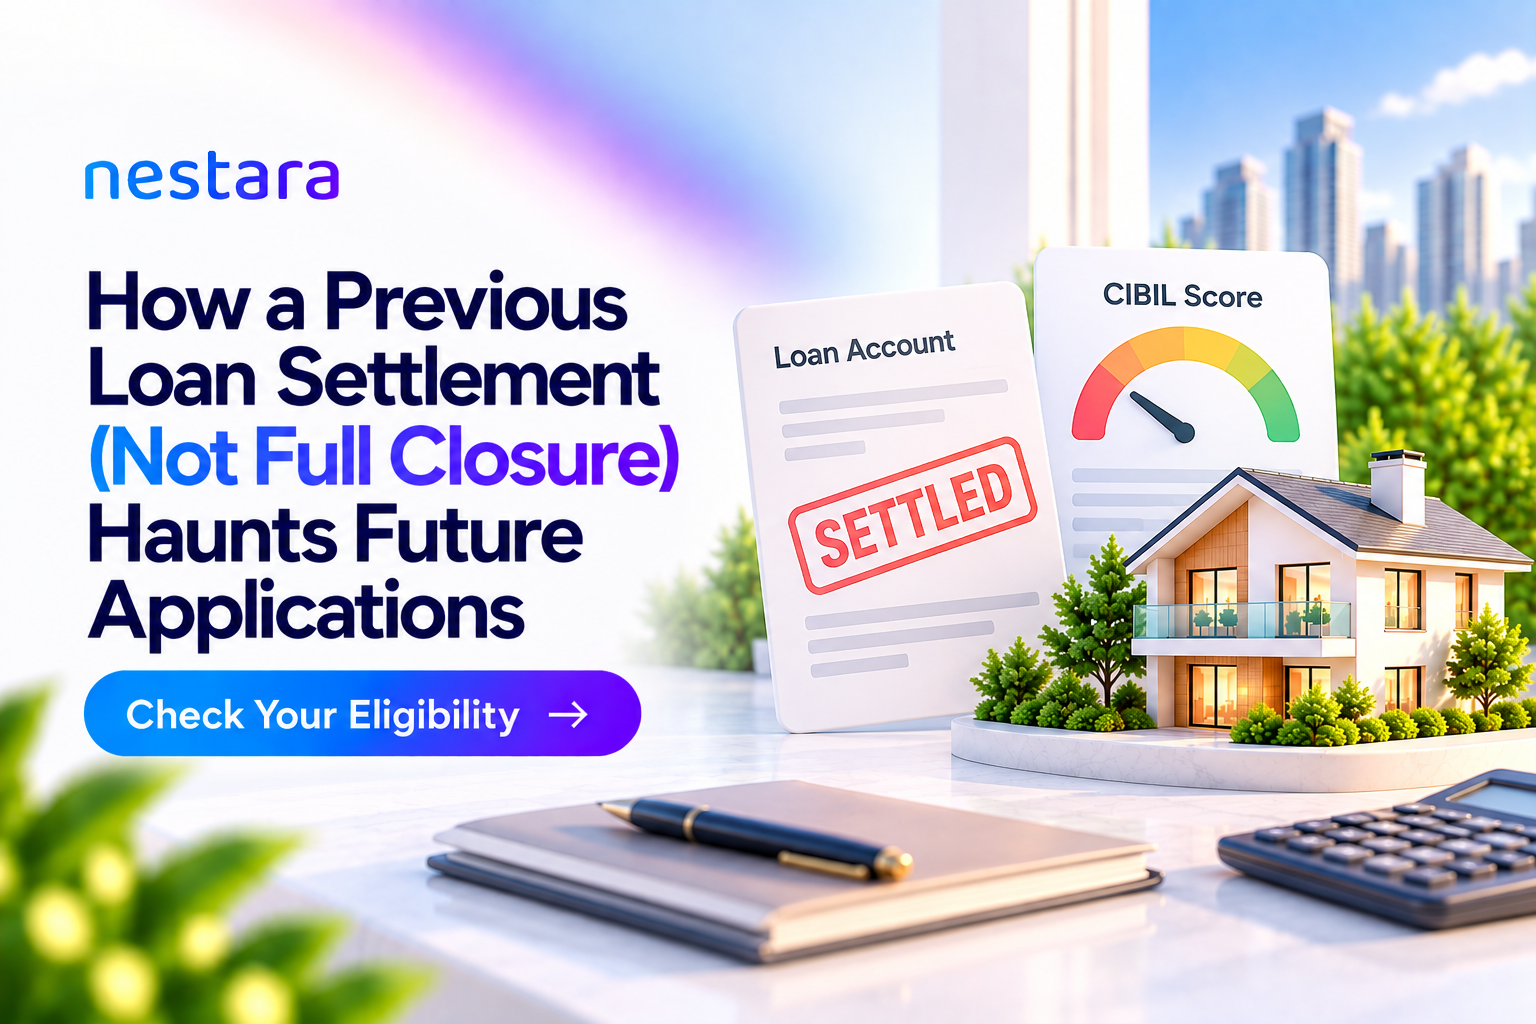
How a Previous Loan Settlement (Not Full Closure) Haunts Future Applications
A loan settlement can make future home loan applications harder because “settled” signals that the lender accepted less than the full amount originally due.
A fully closed loan, by contrast, indicates that the contractual dues were completely repaid; lenders generally view a clean “closed” status more favourably.
What Is the Difference Between Loan Settlement and Full Closure?
A loan is settled when you and the lender agree to repay an amount lower than the total outstanding amount, while a loan is closed when the full amount due has been repaid. The distinction can remain visible in your credit report and can influence how lenders assess future borrowing.
| Loan status | What it generally means | How lenders may view it |
|---|---|---|
| Closed | Full dues have been repaid | Generally positive |
| Settled | Lender accepted less than the total amount due | Can be viewed negatively |
| Written off | Lender has written off an amount it could not recover | Generally viewed negatively |
| Restructured | Loan terms were modified under an approved arrangement | Assessment depends on circumstances |
A settlement is therefore not simply another word for closure. If you paid the entire amount owed, you should expect the account to reflect closure rather than settlement, subject to the lender reporting the information correctly.
Why Does a Settled Loan Affect a Future Home Loan?
A settled account can affect a future home loan because it shows that the previous lender did not receive the full amount originally payable. CIBIL explicitly notes that accounts reported as “written off” or “settled” are not viewed favourably by lenders.
For a home loan, this matters because you are asking a lender to provide a substantial amount over a long repayment period. Your previous repayment behaviour is therefore relevant to the lender’s assessment of credit risk.
A strong current income or otherwise healthy credit profile may help, but it does not automatically erase a previous settlement.
Does a Loan Settlement Lower Your CIBIL Score?
A loan settlement can negatively affect your credit profile, but there is no universal number of points by which your CIBIL Score will fall. CIBIL’s scoring system is proprietary, and the impact depends on your overall credit history and the information reported by lenders.
CIBIL currently states that its score ranges from 300 to 900 and is calculated mainly using factors including payment history, credit utilisation, age of credit and enquiries.
This means you should avoid claims such as “a settlement will reduce your score by exactly 100 points.” There is no reliable universal figure.
More importantly, the “settled” status itself can concern lenders, even if your score later improves.
How Long Does a Settled Loan Stay on Your Credit Report?
There is no simple universal rule that says a settled account will disappear after a specific number of months or years. The account history and reported status form part of your credit information, and lenders can consider that history when evaluating a new application.
CIBIL advises consumers to check their credit report for inaccurate account information and contact the relevant credit institution when corrections are required. CIBIL also cannot independently change account information without confirmation from the credit institution.
So, waiting for the settlement to become “old” is not the same as resolving the settlement status.
Can a Settled Loan Be Changed to “Closed”?
A settled account may be changed to “closed” if you subsequently pay the remaining amount due and the lender confirms the revised status. CIBIL’s own example describes a borrower who paid the remaining amount after settlement, obtained an NOC from the lender and raised a dispute; the status was then changed from “settled” to “closed” after confirmation from the lender.
If you are in this situation:
- Contact the original lender.
- Ask for the exact amount required to clear the remaining liability.
- Pay the amount through the lender’s official process.
- Obtain the appropriate closure/NOC documentation.
- Check your CIBIL Report after the lender has updated its records.
- Raise a dispute if the information remains incorrect.
Do not assume that paying an amount to a third party automatically changes the bureau status. The relevant credit institution must confirm the updated information.
Can You Still Get a Home Loan After a Previous Settlement?
Yes, a previous settlement does not create a universal permanent ban on future borrowing, but it can make approval more difficult because lenders may treat the account as a negative credit signal. The final decision depends on the lender’s credit policy and your complete financial profile.
Your application may be stronger if you can demonstrate:
- Consistent repayment of subsequent loans and credit cards
- Stable and adequately documented income
- Manageable existing EMIs
- No recent payment defaults
- Accurate and up-to-date credit information
- A reasonable loan amount relative to your repayment capacity
A lender may still decline an application if the settlement is considered too significant a risk under its internal policy.
Should You Apply Immediately After Clearing a Settlement?
You should first make sure the credit report accurately reflects the updated account status rather than immediately submitting multiple applications. CIBIL says lenders generally submit updated information within 30–45 days, although reporting timelines can vary, and advises consumers to dispute information that remains incorrect beyond the applicable reporting window.
This is particularly important because CIBIL reports lender enquiries associated with loan and credit-card applications, including enquiries made during the previous 36 months.
Applying repeatedly while your report still shows an unresolved settlement may not improve your chances.
How to Rebuild Your Profile After a Loan Settlement
The best way to recover from a past settlement is to build a consistent record of responsible credit behaviour over time. There is no guaranteed “quick fix,” but several practical steps can strengthen your profile.
1. Clear the remaining liability if possible
If you can legitimately convert the settlement status to a closed status by paying the remaining amount agreed with the lender, discuss the process directly with that lender.
2. Pay every current obligation on time
Recent repayment behaviour matters. Avoid missing EMIs or credit-card payments while trying to recover your credit profile.
3. Keep new borrowing under control
Avoid taking unnecessary loans or making multiple applications simply to find out which lender will approve you.
4. Check your credit report before applying
Your CIBIL Report contains account and enquiry information that lenders may review. Checking your own report does not hurt your CIBIL Score.
You can use our Free Credit Score Check to make checking your credit position part of your home-loan preparation. Review the account statuses, outstanding balances and recent enquiries rather than looking only at the headline score.
Conclusion
A previous loan settlement can haunt a future home loan application because settled and closed are not equivalent credit statuses. A settlement tells a future lender that the earlier debt was resolved for less than the full amount originally due, which can raise concerns about repayment behaviour.
The good news is that a past settlement does not mean you can never qualify for a home loan. If possible, work with the original lender to resolve the remaining liability and have the account accurately updated. Then focus on timely repayments, manageable borrowing and a clean, accurate credit report.
Before approaching a home loan lender, use our Free Credit Score Check to understand what your current credit profile actually shows. Knowing your position first can help you approach your next home loan application more strategically.
FAQs
Is a settled loan the same as a closed loan?
No. A settled loan means the lender accepted an amount lower than the total amount originally due. A closed loan indicates that the full dues were repaid.
Can a settled loan cause a home loan rejection?
Yes, it can contribute to rejection because lenders may view a “settled” account as a negative credit signal. However, it is not an automatic rejection under every lender’s policy.
Can I get a home loan with a settled account on my CIBIL Report?
You may still be able to obtain a home loan, but the settlement can make approval more difficult. Lenders assess your complete credit and financial profile, not just one account or your CIBIL Score.
Can I remove “settled” from my CIBIL Report?
You cannot simply ask CIBIL to delete accurate information. If you subsequently clear the remaining liability and the lender agrees to update the account status, you can ask the lender to report the corrected status and then check or dispute the report if necessary.
How long does it take for a corrected loan status to appear?
The timing depends on the lender’s reporting process. CIBIL says credit institutions generally submit data within 30–45 days, and inaccurate information can be disputed when the relevant reporting information remains outdated.
Does checking my own CIBIL Score reduce it?
No. Checking your own CIBIL Score does not impact the score. CIBIL specifically states that self-checking does not hurt your score.
How often can I get a free CIBIL Score and Report?
CIBIL currently provides one free CIBIL Score and Report per calendar year.