How a 0.5% Rate Cut Changes Your EMI on a ₹50 Lakh Loan (Worked Example)
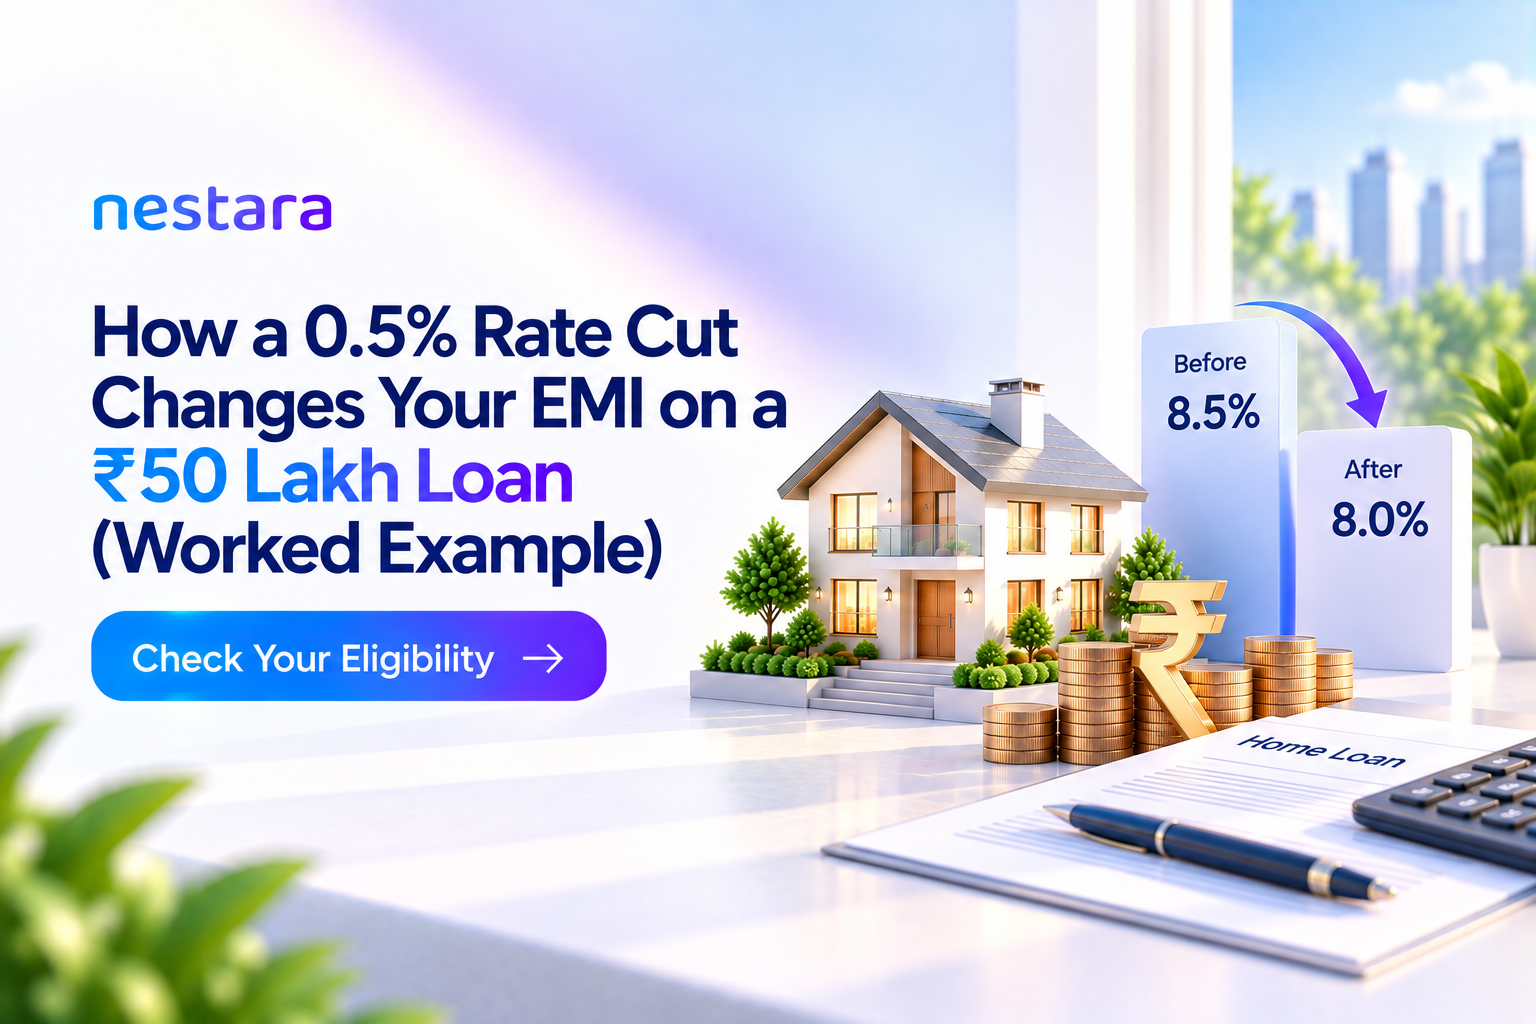
A 0.5 percentage-point cut in your home loan interest rate can reduce the EMI on a ₹50 lakh, 20-year loan by about ₹1,569 per month, if the rate falls from 8.5% to 8% and the outstanding principal and tenure remain unchanged. Over the remaining 20 years, that could mean roughly ₹3.77 lakh less in total interest, before considering any fees or changes in repayment terms.
But the actual impact depends on your outstanding balance, remaining tenure, current rate, and how your lender applies the rate change. Here is a worked example to show exactly how the numbers move.
What does a 0.5% home loan rate cut mean for your EMI?
A 0.5% rate cut means the annual interest rate falls by 0.50 percentage points, not that your existing interest rate is reduced by 0.5% of itself.
For example:
- Current rate: 8.50% p.a.
- New rate: 8.00% p.a.
- Loan amount: ₹50 lakh
- Remaining tenure: 20 years
- Rate reduction: 0.50 percentage points
For a borrower with the same ₹50 lakh principal and 20-year tenure, the EMI changes as follows:
| Particulars | At 8.50% | At 8.00% |
|---|---|---|
| Loan amount | ₹50 lakh | ₹50 lakh |
| Tenure | 20 years | 20 years |
| Monthly EMI | ₹43,391 | ₹41,822 |
| Total interest | ₹54.14 lakh | ₹50.37 lakh |
| Total repayment | ₹1.04 crore | ₹1.00 crore |
Illustrative calculation. Actual lender calculations may vary slightly because of rounding, reset dates and loan-specific terms.
The result is an EMI reduction of approximately ₹1,569 a month, or around ₹18,830 a year.
How much interest can you save after a 0.5% rate cut?
A 0.5 percentage-point reduction can save about ₹3.77 lakh in interest in this specific example if the ₹50 lakh balance and full 20-year tenure remain unchanged.
The calculation is:
- Interest at 8.50%: approximately ₹54.14 lakh
- Interest at 8.00%: approximately ₹50.37 lakh
- Approximate interest saving: ₹3.77 lakh
This is why a rate cut should not be judged only by the monthly EMI reduction. A seemingly small change in the interest rate can have a meaningful effect over a long repayment period.
However, this ₹3.77 lakh figure assumes the full ₹50 lakh remains outstanding for 20 years. If you have already repaid a significant part of the loan or have only a few years left, the savings will be different.
Why does the same 0.5% cut affect borrowers differently?
The impact of a 0.5% rate cut depends mainly on the outstanding principal and remaining tenure, not just the original loan amount.
For example, consider two borrowers who both receive a 0.5 percentage-point reduction:
| Factor | Borrower A | Borrower B |
|---|---|---|
| Outstanding loan | ₹50 lakh | ₹25 lakh |
| Remaining tenure | 20 years | 10 years |
| Rate before cut | 8.5% | 8.5% |
| Rate after cut | 8.0% | 8.0% |
Borrower A will generally see a larger absolute EMI and interest saving because the outstanding balance is higher and the rate difference applies over a longer period.
This is also why the same rate reduction may feel significant early in a loan but have a smaller effect when only a few years remain.
Does a 0.5% rate cut automatically reduce your EMI?
A 0.5% rate cut does not always mean your EMI will immediately fall by the amount shown in a simple calculator.
For floating-rate loans, a change in the applicable benchmark can affect the interest rate, but the lender may adjust the EMI, tenure, or both according to the loan terms and applicable framework. RBI’s framework for floating-rate EMI-based personal loans requires lenders to communicate the impact of benchmark changes and provide applicable options around EMI, tenure and prepayment.
For bank floating-rate retail loans linked to an external benchmark, the benchmark is required to reset at least once every three months.
So, after a rate cut, check your lender’s:
- New applicable interest rate
- Reset date
- Revised EMI
- Remaining tenure
- Outstanding principal
- Applicable conversion or other charges
The MPC or benchmark change itself does not guarantee a particular EMI reduction.
Should you reduce your EMI or keep paying the same EMI?
If your rate falls but you can continue paying the old EMI, keeping the EMI unchanged can help you repay the loan faster.
For example, instead of using the entire benefit of a rate cut to reduce your monthly payment, you could continue paying approximately ₹43,391 even after the rate falls to 8%. More of each payment can then go toward principal, potentially shortening the repayment period and reducing total interest.
If monthly cash flow is your priority, reducing the EMI to approximately ₹41,822 may provide immediate relief.
The better choice depends on your financial situation:
- Need monthly cash-flow relief? A lower EMI may help.
- Can comfortably maintain the existing EMI? Continuing it can accelerate repayment.
- Planning a major expense? The lower EMI may create additional monthly flexibility.
- Already have surplus cash? Compare rate reduction with a partial prepayment.
How can you calculate your own 0.5% rate-cut impact?
The easiest way to estimate your own savings is to compare your current loan rate with the rate after the 0.5 percentage-point reduction while keeping the outstanding balance and remaining tenure unchanged.
For example, enter:
- Outstanding principal
- Current interest rate
- New interest rate
- Remaining tenure
Our EMI Calculator lets you compare the EMI, principal, interest and total repayment under different combinations.
This is particularly useful when your lender tells you that your rate has changed but you want to understand what the change actually means for your household budget.
Is a 0.5% rate cut enough to consider a balance transfer?
A 0.5% lower rate can be worth evaluating, but the rate difference alone should not decide whether you transfer your home loan.
Compare:
- Outstanding principal
- Remaining tenure
- Current EMI
- New EMI
- Total interest under both options
- Processing and other transfer-related costs
- Any applicable conversion or administrative charges
- Break-even period
A lower rate is useful only when the overall savings outweigh the costs and the new loan terms work for you.
What should you do after a 0.5% rate cut?
A rate cut is a good reason to review your home loan, but not necessarily a reason to change it immediately.
Use this simple checklist:
- Check your current outstanding balance.
- Confirm the new interest rate and reset date.
- Calculate the revised EMI.
- Compare total interest, not just monthly savings.
- Check whether keeping the old EMI can shorten your tenure.
- Compare a balance transfer if your current rate remains materially higher.
- Consider all applicable transfer or conversion costs.
The important number is not simply “0.5%.” It is the rupee value of that rate change over the time you still have left on your loan.
Conclusion
A 0.5 percentage-point rate cut on a ₹50 lakh home loan can reduce the EMI by about ₹1,569 a month in a 20-year example where the rate falls from 8.5% to 8%. If the entire ₹50 lakh remains outstanding for the full 20 years, the illustrative interest saving is about ₹3.77 lakh.
Your actual savings may be higher or lower depending on your outstanding balance, remaining tenure, lender’s reset mechanism and other loan terms.
Before deciding what to do with the rate reduction, run your own numbers. Use our EMI Calculator to compare different rates and repayment periods, and if your current rate is significantly higher than available alternatives, evaluate the potential savings from a balance transfer as well.
FAQs
How much does a 0.5% rate cut reduce EMI on a ₹50 lakh loan?
For a ₹50 lakh loan with a 20-year tenure, a reduction from 8.5% to 8% lowers the illustrative EMI from about ₹43,391 to ₹41,822—a reduction of approximately ₹1,569 per month.
How much interest can I save with a 0.5% rate cut?
In the ₹50 lakh, 20-year example, total interest falls from about ₹54.14 lakh to ₹50.37 lakh, producing an illustrative saving of approximately ₹3.77 lakh.
Does a 0.5% rate cut always reduce my EMI?
No. The lender may adjust the EMI, tenure, or both depending on the loan terms and applicable rate-reset framework. Check your revised repayment schedule after the rate reset.
Is a 0.5% rate cut significant for a home loan?
It can be significant over a long tenure because even a small reduction in the annual interest rate can affect every monthly repayment. The actual benefit depends on your outstanding balance and remaining tenure.
Should I reduce my EMI after a rate cut or keep it unchanged?
If you need monthly cash-flow relief, reducing the EMI can help. If you can afford the existing EMI, continuing with the higher payment can help repay principal faster and potentially reduce total interest.
Should I transfer my home loan for a 0.5% lower rate?
Not necessarily. Compare the potential interest saving with transfer-related costs, your outstanding balance, remaining tenure and the new lender’s terms before deciding.